All 3 Singapore-listed banks in DBS Group Holdings Limited (SGX: D05), United Overseas Bank Limited (SGX: U11), and Oversea-Chinese Banking Corporation Limited (SGX: O39) have released their business updates for the 3rd quarter and the first 9 months of FY2026.
I have separately reviewed their financial performance, covering the year-on-year changes in their financial figures for both the 3rd quarter and the first 9 months of FY2026, as well as the quarter-on-quarter movements in their key financial ratios for the 3rd quarter. You can read my individual reviews via the links below:
UOB (Results Released on 04 November 2026) – United Overseas Bank Limited (SGX: U11): 3Q & 9M FY2026 Business Update Review
DBS (Results Released on 05 November 2026) – DBS Group Holdings Limited (SGX: D05): 3Q & 9M FY2026 Business Update Review
OCBC (Results Released on 06 November 2026) – Oversea-Chinese Banking Corporation Limited (SGX: O39): 3Q & 9M FY2026 Business Update Review
In this post, I will bring together the financial figures and key financial ratios of all three banks for a side-by-side comparison, to assess which of them delivered the strongest overall performance this time round.
Beyond their financial performance, I will also compare their latest valuations to see whether DBS still commands the title of the ‘most expensive’ among the three, while UOB remains the ‘cheapest’.
Financial Results Comparison: 3Q FY2025 vs. 3Q FY2026:
Net Interest Income:
| DBS | UOB | OCBC | |
| Net Interest Income | Up +3.7% 3Q FY2025: S$3,578m 3Q FY2026: S$3,711m | Up +0.6% 3Q FY2025: S$2,265m 3Q FY2026: S$2,278m | Up +3.9% 3Q FY2025: S$2,226m 3Q FY2026: S$2,313m |
All 3 banks recorded an improvement in net interest income in the 3rd quarter, with DBS and OCBC posting similar gains. OCBC narrowly outperformed DBS, recording a 3.9% increase compared to DBS’s 3.7%.
Net Fee & Commission Income:
| DBS | UOB | OCBC | |
| Net Fee & Commission Income | Up +5.5% 3Q FY2025: S$1,357m 3Q FY2026: S$1,432m | Up +19.2% 3Q FY2025: S$615m 3Q FY2026: S$733m | Up +7.6% 3Q FY2025: S$683m 3Q FY2026: S$735m |
All 3 banks once again recorded year-on-year growth in net fee and commission income. UOB led by a wide margin, with a 19.2% increase, driven by strong growth in wealth management, card-related and loan-related activities, significantly outpacing its 2 peers.
Other Non-Interest Income:
| DBS | UOB | OCBC | |
| Other Non- Interest Income | Down -29.6% 3Q FY2025: S$997m 3Q FY2026: S$702m | Down -28.6% 3Q FY2025: S$518m 3Q FY2026: S$370m | Down -22.8% 3Q FY2025: S$887m 3Q FY2026: S$685m |
All 3 banks recorded a decline in other non-interest income, which dragged down their total income despite improvements in both net interest income and net fee and commission income. OCBC saw the smallest decline at 22.8%, followed by UOB at 28.6% and DBS at 29.6%.
Net Profit Attributable to Shareholders:
| DBS | UOB | OCBC | |
| Net Profit Attributable to Shareholders | Down -4.8% 3Q FY2025: S$2,954m 3Q FY2026: S$2,813m | Up +182.2% 3Q FY2025: S$443m 3Q FY2026: S$1,250m | Up +3.2% 3Q FY2025: S$1,978m 3Q FY2026: S$2,042m |
DBS was the only bank to report a year-on-year decline in net profit, falling 4.8%, while both UOB and OCBC recorded growth. UOB posted the stronger improvement, largely driven by a significant reduction in credit and other losses.
Financial Results Comparison: 9M FY2025 vs. 9M FY2026:
Net Interest Income:
| DBS | UOB | OCBC | |
| Net Interest Income | Down -1.1% 9M FY2025: S$10,907m 9M FY2026: S$10,786m | Down -1.6% 9M FY2025: S$7,009m 9M FY2026: S$6,900m | Down -0.8% 9M FY2025: S$6,845m 9M FY2026: S$6,798m |
As expected, all 3 banks recorded a decline in net interest income amid a contraction in net interest margins. OCBC saw the smallest drop at 0.8%, followed by DBS at 1.1% and UOB at 1.6%.
Net Fee & Commission Income:
| DBS | UOB | OCBC | |
| Net Fee & Commission Income | Up +15.1% 9M FY2025: S$3,799m 9M FY2026: S$4,374m | Up +4.6% 9M FY2025: S$1,945m 9M FY2026: S$2,035m | Up +18.8% 9M FY2025: S$1,809m 9M FY2026: S$2,150m |
Net fee and commission income was the only business segment in which all 3 banks recorded year-on-year growth in 9M FY2026. OCBC led the pack with an 18.8% increase, followed by DBS at 15.1% and UOB at 4.6%.
Other Non-Interest Income:
| DBS | UOB | OCBC | |
| Other Non- Interest Income | Down -4.8% 9M FY2025: S$2,863m 9M FY2026: S$2,726m | Down -6.5% 9M FY2025: S$1,565m 9M FY2026: S$1,464m | Up +19.2% 9M FY2025: S$2,335m 9M FY2026: S$2,783m |
OCBC was the only bank to record year-on-year growth in other non-interest income, posting a strong 19.2% increase. This was driven by double-digit growth in both trading and insurance income.
Net Profit Attributable to Shareholders:
| DBS | UOB | OCBC | |
| Net Profit Attributable to Shareholders | Up +1.7% 9M FY2025: S$8,675m 9M FY2026: S$8,822m | Up +27.3% 9M FY2025: S$3,271m 9M FY2026: S$4,165m | Up +9.9% 9M FY2025: S$5,677m 9M FY2026: S$6,237m |
All 3 banks recorded year-on-year growth in net profit for the first 9 months of FY2026. UOB delivered the strongest improvement, with a 27.3% increase, largely attributable to a significant reduction in its allowances for credit and other losses.
Key Financial Ratios Comparison: 2Q FY2026 vs. 3Q FY2026:
Net Interest Margin:
| DBS | UOB | OCBC | |
| Net Interest Margin | No Change 2Q FY2026: 1.87% 3Q FY2026: 1.87% | Down -0.06pp 2Q FY2026: 1.74% 3Q FY2026: 1.68% | Down -0.04pp 2Q FY2026: 1.70% 3Q FY2026: 1.66% |
DBS was the only bank to maintain its net interest margin at the previous quarter’s level, while both UOB and OCBC recorded quarter-on-quarter declines. It also continued to lead its peers in this area, with the highest net interest margin of 1.87%, compared to 1.68% for UOB and 1.66% for OCBC.
Return on Equity:
| DBS | UOB | OCBC | |
| Return on Equity | Down -1.9pp 2Q FY2026: 17.9% 3Q FY2026: 16.0% | Down -1.7pp 2Q FY2026: 11.8% 3Q FY2026: 10.1% | Down -1.3pp 2Q FY2026: 14.4% 3Q FY2026: 13.1% |
All 3 banks reported a quarter-on-quarter decline in return on equity in the 3rd quarter, with OCBC experiencing the smallest contraction of 1.3 percentage points, followed by UOB at 1.7 percentage points and DBS at 1.9 percentage points.
Despite the declines, DBS continued to lead its peers with the highest return on equity at 16.0%, followed by OCBC at 13.1% and UOB at 10.1%.
Non-Performing Loans Ratio:
| DBS | UOB | OCBC | |
| Non-Performing Loans Ratio | Down -0.1pp 2Q FY2026: 1.0% 3Q FY2026: 0.9% | Down -0.1pp 2Q FY2026: 1.6% 3Q FY2026: 1.5% | Down -0.1pp 2Q FY2026: 0.9% 3Q FY2026: 0.8% |
All 3 banks recorded a quarter-on-quarter improvement in their non-performing loan ratios, with each seeing a 0.1 percentage point decline. OCBC had the lowest ratio at 0.8%, followed by DBS at 0.9% and UOB at 1.5%.
Which Bank Came Out on Top for 3Q & 9M FY2026?
OCBC once again stood out in the 3rd quarter, recording the strongest year-on-year growth in net interest income (in percentage terms) among the 3. banks, alongside the smallest decline in other non-interest income.
For 9M FY2026, OCBC also led in net fee and commission income and other non-interest income growth, while experiencing the smallest year-on-year contraction in net interest margin.
Additionally, the bank recorded the smallest quarter-on-quarter decline in return on equity and maintained the lowest non-performing loan ratio among the three banks, at just 0.8%.
Valuation Comparison (Based on Market Close on 06 November 2026):
| DBS | UOB | OCBC | |
| Share Price | S$69.72 | S$36.88 | S$27.73 |
| P/E Ratio | 11.84 | 6.84 | 16.01 |
| P/B Ratio | 2.87 | 1.28 | 2.03 |
| Dividend Yield ** | 4.39% | 4.91% | 3.57% |
** – The dividend yields for the 3 banks are calculated using their total FY2025 dividend payouts, including any special dividends: S$3.06 per share for DBS, S$1.81 per share for UOB, and S$0.99 per share for OCBC.
For many quarters, DBS had consistently been the most expensive among the 3 banks, but this is no longer the case. OCBC has now taken over that position, commanding the highest P/E ratio while offering the lowest dividend yield among its peers.
At the other end of the spectrum, UOB remains the cheapest of the 3, with the lowest P/E and P/B ratios, alongside the highest dividend yield.
Closing Thoughts
To wrap things up, all 3 Singapore banks reported weaker total income in the 3rd quarter, largely due to a decline in other non-interest income. This came despite improvements in their other two reportable income segments, namely net interest income and net fee and commission income. In terms of net profit, DBS was the only bank to record a year-on-year decline, while both UOB and OCBC posted growth.
For the first 9 months of FY2026, DBS and OCBC managed to grow both their total income and net profit, while UOB saw a decline in total income.
So, which bank came out strongest this time round? OCBC was the clear standout, outperforming its peers in its financial results for both the 3rd quarter and the first 9 months of FY2026, as well as across several key financial ratios. As for DBS, its 3rd quarter performance was admittedly less impressive. However, as I highlighted in my review of its latest results, one relatively weaker quarter does not define the bank. Its underlying fundamentals remain solid, and I see no reason for concern at this point.
Finally, turning to valuations, DBS is no longer the most expensive among the 3 banks. That position has now shifted to OCBC, which commands the highest P/E ratio while offering the lowest dividend yield. UOB, meanwhile, continues to be the cheapest of the 3, with the lowest P/E and P/B ratios, alongside the highest dividend yield.
Disclaimer: At the time of writing, I am a shareholder of DBS, UOB, and OCBC.
Join Me for a FREE Live Online Chit-Chat on Thursday, 12 November, from 8–9pm (SGT)!
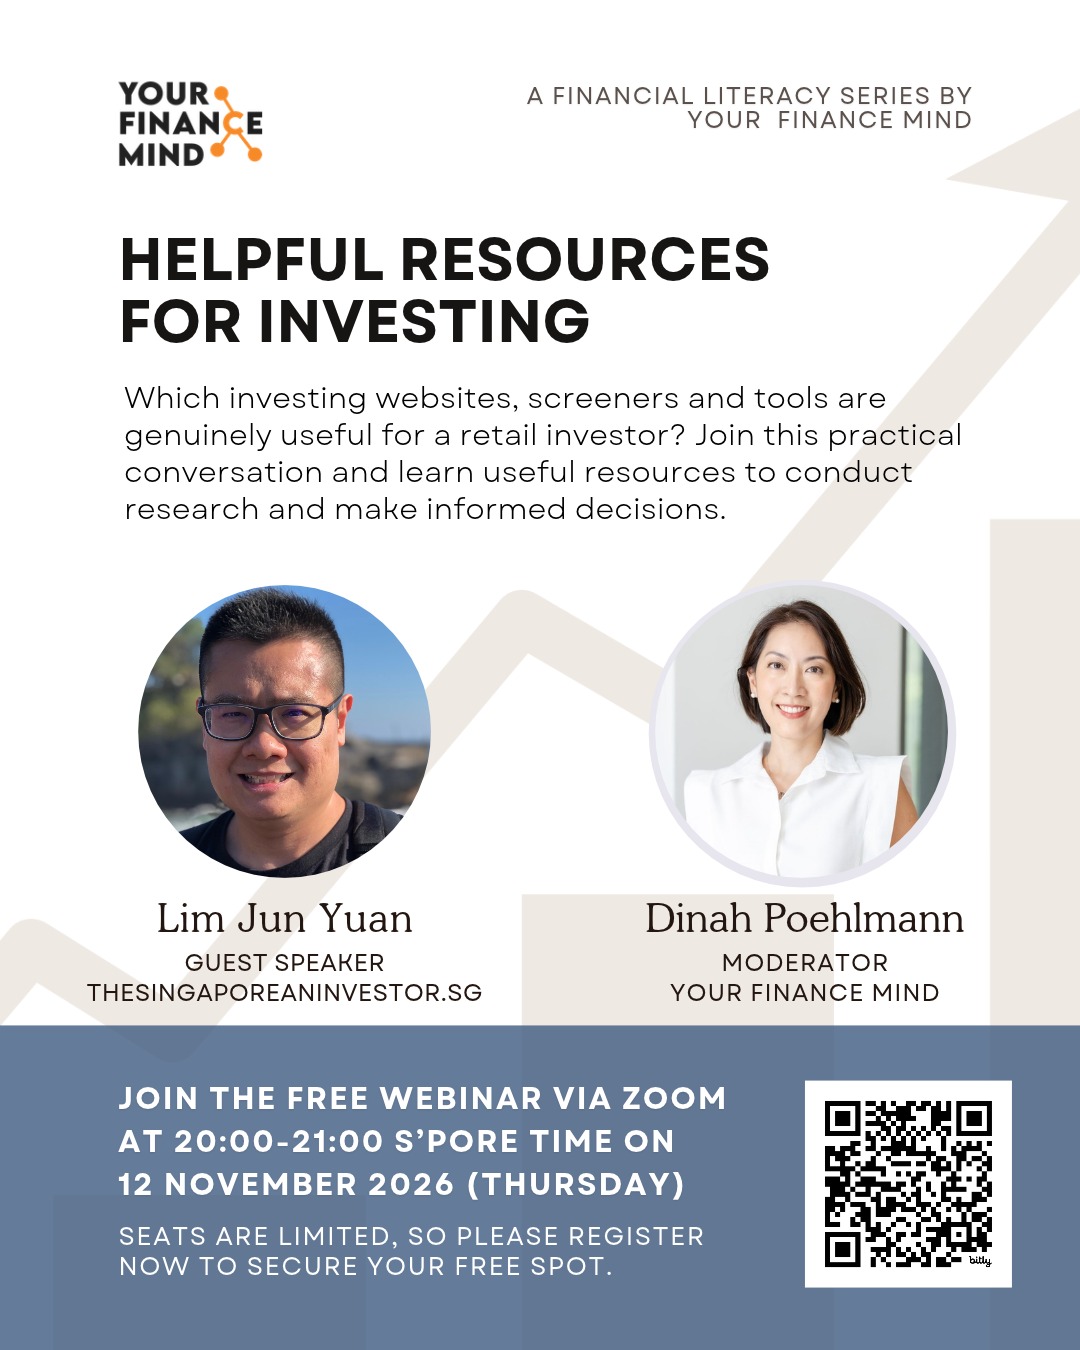
It's been quite some time since I last had a live chit-chat with the investing community, and I’m excited to be back for another session! A big thank you to my friend, Dinah Poehlmann from Your Finance Mind, for inviting me once again!
This time, we’re taking a little break from REITs and exploring some interesting topics surrounding investing, including my go-to investing resources, when is a stock considered 'investable', my thoughts about using AI for stock analysis and trading, and much more.
Whether you're just starting your investing journey or have been investing for years, I hope this session will offer some useful perspectives and practical takeaways that you can apply to your own investing journey.
Best of all, the session is completely FREE to attend! All you need to do is register in advance to receive the Zoom link:
👉 Click here to reserve your spot!
Are You Worried about Not Having Enough Money for Retirement?
You're not alone. According to the OCBC Financial Wellness Index, only 62% of people in their 20s and 56% of people in their 30s are confident that they will have enough money to retire.
But there is still time to take action. One way to ensure that you have a comfortable retirement is to invest in real estate investment trusts (REITs).
In 'Building Your REIT-irement Portfolio' which I've authored, you will learn everything you need to know to build a successful REIT investment portfolio, including a list of 9 things to look at to determine whether a REIT is worthy of your investment, 1 simple method to help you maximise your returns from your REIT investment, 4 signs of 'red flags' to look out for and what you can do as a shareholder, and more!

You can find out more about the book, and grab your copy (ebook or physical book) here...

Comments (0)