Brief Overview:
Mapletree Logistics Trust (SGX: M44U), or MLT, is a Singapore-listed REIT that focuses on investing in logistics properties across the Asia-Pacific region.
As of 30 September 2026, MLT’s portfolio consists of 172 properties spanning 9 markets: Singapore, Australia, China, Hong Kong, India, Japan, Malaysia, South Korea, and Vietnam, with total assets under management of S$13.1 billion.
Financial Figures (1H FY2025/26 vs. 1H FY2026/27):
| 1H FY2025/26 | 1H FY2026/27 | % Variance | |
| Gross Revenue (S$’mil) | $354.9m | $358.9m | +1.1% |
| Property Operating Expenses (S$’mil) | $48.2m | $47.7m | -1.0% |
| Net Property Income (S$’mil) | $306.7m | $311.2m | +1.5% |
| Distributable Income to Unitholders (S$’mil) | $184.5m | $186.3m | +1.0% |
Overall, MLT delivered a stable set of financial results for 1H FY2026/27, with gross revenue, net property income, and distributable income to unitholders all registering year-on-year growth of around 1%.
Gross revenue increased by 1.1% year on year to S$358.9 million. This was mainly driven by a full-period contribution from the completed redevelopment of Mapletree Joo Koon, contributions from an acquisition in India completed in 4Q FY2025/26, organic growth across its existing portfolio (particularly in Singapore and South Korea), as well as the strengthening of the Chinese Yuan, Australian Dollar, and Malaysian Ringgit against the Singapore Dollar. These positive factors were partially offset by the absence of contributions from divested properties and the depreciation of the Japanese Yen and South Korean Won against the Singapore Dollar.
With higher gross revenue and a 1.0% year-on-year decline in property operating expenses (largely attributable to the absence of expenses associated with divested properties), MLT’s net property income rose by 1.5% year on year to S$311.2 million.
Finally, the increase in net property income, coupled with a 0.9% year-on-year reduction in borrowing costs, contributed to a 1.0% year-on-year rise in MLT’s distributable income to unitholders to S$186.3 million.
Financial Figures (2Q FY2025/26 vs. 2Q FY2026/27):
| 2Q FY2025/26 | 2Q FY2026/27 | % Variance | |
| Gross Revenue (S$’mil) | $177.5m | $180.0m | +1.4% |
| Property Operating Expenses (S$’mil) | $24.2m | $25.2m | +4.1% |
| Net Property Income (S$’mil) | $153.3m | $154.8m | +1.0% |
| Distributable Income to Unitholders (S$’mil) | $92.5m | $93.3m | +0.9% |
MLT recorded a similar improvement in its financial performance for the 2nd quarter of FY2026/27, with gross revenue, net property income, and distributable income to unitholders all registering modest year-on-year growth of around 1%. Given that this came after 2 consecutive financial years (FY2024/25 and FY2025/26) in which the REIT reported weaker results in every quarter, I view this as an encouraging set of results.
Gross revenue rose by 1.4% year on year to S$180.0 million, primarily driven by higher contributions from the completed redevelopment of Mapletree Joo Koon Logistics Hub, the acquisition in India completed in 4Q FY2025/26, and organic growth across its existing portfolio, particularly in Singapore. The appreciation of several currencies against the Singapore Dollar, notably the Chinese Yuan and Australian Dollar, also provided a boost. These positive contributions were partly offset by the absence of income from divested properties and the depreciation of the Japanese Yen against the Singapore Dollar.
However, property operating expenses increased by 4.1% year on year, outpacing the 1.4% growth in gross revenue, mainly due to higher property taxes. As a result, MLT’s NPI grew at a more modest pace of 1.0% year on year to S$154.8 million.
Portfolio Occupancy Profile (1Q FY2026/27 vs. 2Q FY2026/27):
| 1Q FY2026/27 | 2Q FY2026/27 | |
| Portfolio Occupancy (%) | 96.4% | 96.4% |
| Portfolio WALE (by Net Lettable Area – years) | 2.5 years | 2.5 years |
| Rental Reversion (%) | +0.9% | +2.1% |
Compared with the previous quarter, MLT’s portfolio occupancy remained stable at 96.4%. At the geographical level, China was the only market with occupancy below 95%, at 94.4%. Even so, its occupancy improved by 0.6 percentage point quarter on quarter. All the other geographical markets maintained occupancy rates of at least 95%, which I consider to be a healthy level.
Turning to rental reversions for new and renewed leases, all geographical markets except China continued to record positive rental reversions, ranging from +0.5% in Hong Kong to +6.3% in South Korea. While rental reversions in China remained negative, the rate of decline has continued to narrow progressively over the past several quarters, improving from -12.2% in 2Q FY2024/25 to -1.7% in 2Q FY2026/27, as illustrated below:
-12.2% (2Q FY2024/25) → -10.2% (3Q) → -9.4% (4Q) → -7.5% (1Q FY2025/26) → -3.0% (2Q) → -2.2% (3Q) → -2.0% (4Q) → -1.8% (1Q FY2026/27) → -1.7% (2Q)
Looking ahead at its lease expiry profile, 15.9% of MLT’s leases are due for renewal in the second half of FY2026/27. The proportion rises significantly to 34.0% in FY2027/28, representing the largest concentration of lease expiries over the periods highlighted. A further 34.5% of leases are scheduled to expire in FY2028/29 and beyond.
Debt Profile (1Q FY2026/27 vs. 2Q FY2026/27):
| 1Q FY2026/27 | 2Q FY2026/27 | |
| Aggregate Leverage (%) | 40.5% | 37.5% |
| Interest Coverage Ratio (times) | 2.9x | 2.9x |
| Average Cost of Debt (%) | 2.6% | 2.7% |
| Average Term to Debt Maturity (years) | 3.5 years | 3.4 years |
| % of Borrowings Hedged at Fixed Rates (%) | 82.0% | 90.0% |
MLT’s debt profile improved compared with the previous quarter, with its aggregate leverage declining by 3.0 percentage points to a healthy 37.5%. This was partly attributable to the use of proceeds from the S$400 million perpetual securities issued in August 2026, which carry a lower cost of funding, to repay bank loans ahead of the planned redemption of an existing S$400 million perpetual securities issue in November 2026.
Another notable improvement was the significant increase in the proportion of borrowings hedged at fixed interest rates, which reached 90%. This places MLT among the Singapore REITs with the highest levels of fixed-rate debt hedging, providing it with a substantial buffer against potential adverse interest rate movements. This is particularly relevant given concerns over persistent inflation and the possibility of further increases in benchmark borrowing rates by the US Federal Reserve.
MLT’s debt maturity profile is also well staggered, helping to spread out its refinancing requirements. Only 2% of its borrowings are due for refinancing in the second half of FY2026/27. Over the following 5 financial years, from FY2027/28 to FY2031/32, an average of approximately 18% of borrowings will mature each year, while the remaining 7% will not fall due for refinancing until FY2032/33 or later.
Distribution Payout to Unitholders (2Q FY2025/26 vs. 2Q FY2026/27):
As a unitholder of MLT, you can expect to receive distributions on a quarterly basis.
The table below compares MLT’s distribution payout for 2Q FY2026/27 with the corresponding quarter a year earlier:
| 2Q FY2025/26 | 2Q FY2026/27 | % Variance | |
| Distribution Per Unit (S$’cents) | 1.815 cents | 1.816 cents | +0.1% |
Notably, this is the second consecutive quarter in which MLT has recorded year-on-year growth in its distribution payout. Although the increase was marginal at just 0.1%, I still consider it an encouraging sign, especially given that distributions had been declining year on year over the preceding 2 financial years before the current financial year.
For existing MLT unitholders, here are the key dates to take note of for the upcoming distribution payout:
Ex-Date: 04 November 2026
Record Date: 05 November 2026
Payout Date: 17 December 2026
Distribution Payout to Unitholders (1H FY2025/26 vs. 1H FY2026/27):
Including the distribution of 1.816 cents per unit declared in the first quarter, MLT’s total distribution payout for 1H FY2026/27 stands at 3.632 cents per unit.
The table below compares MLT’s distribution payout for the first half of FY2026/27 with the corresponding period a year ago:
| 1H FY2025/26 | 1H FY2026/27 | % Variance | |
| Distribution Per Unit (S$’cents) | 3.627 cents | 3.632 cents | +0.1% |
CEO Ms Jean Kam’s Comments & Outlook (from the REIT’s Press Release):
“MLT delivered a resilient quarter, supported by healthy leasing demand and proactive asset management. We also made good progress on capital management, issuing S$400 million of lower-rate perpetual securities to replace an existing issuance, and our inaugural offshore RMB bond at a competitive 2.1% coupon.
We continued to advance our portfolio rejuvenation strategy with approximately S$243 million of divestments in China, Hong Kong, Singapore and Australia during 1H FY26/27. Capital recycled from these divestments provides capacity for reinvestment in high-specification logistics space, starting with our fifth redevelopment project in Singapore, at 9 and 15 Changi South Street 2. This continued investment reinforces MLT’s market-leading position in Singapore, our largest core market. With regard to 201 Keppel Road, the deferment of the Sponsor’s call option also preserves the potential to unlock further value, supporting MLT’s longer term growth.”
Closing Thoughts:
Overall, in my personal opinion, MLT delivered another encouraging set of quarterly results.
From a financial perspective, it is pleasing to see the REIT recording year-on-year growth in its quarterly financial figures for the second consecutive quarter. The same positive trend is also evident in its distribution payout to unitholders.
Occupancy across its geographical markets also remains healthy, with all locations except China achieving occupancy rates of at least 95%. Even in China, occupancy was not far off at 94.4%, representing a 0.6 percentage point improvement compared with the previous quarter.
While China remains the only market where rental reversions are still negative, the situation has continued to improve progressively every quarter, with the rental reversion rate narrowing from -12.2% in 2Q FY2024/25 to -1.7% in 2Q FY2026/27.
Finally, MLT’s debt profile remains in a healthy position, with aggregate leverage at 37.5%, leaving a comfortable buffer below the regulatory limit of 50.0%. I am also encouraged by the fact that 90% of its borrowings are hedged at fixed interest rates, providing the REIT with a substantial cushion against potential adverse interest rate movements.
Related Documents:
Press Release
Financial Statements
Presentation Slides
Reviews of Results Posted by Other Mapletree REITs:
Mapletree Industrial Trust (SGX: ME8U): 2Q & 1H FY2026/27 Results Review
Disclaimer: At the time of writing, I am a unitholder of Mapletree Logistics Trust.
Join Me for a FREE Live Online Chit-Chat on Thursday, 12 November, from 8–9pm (SGT)!
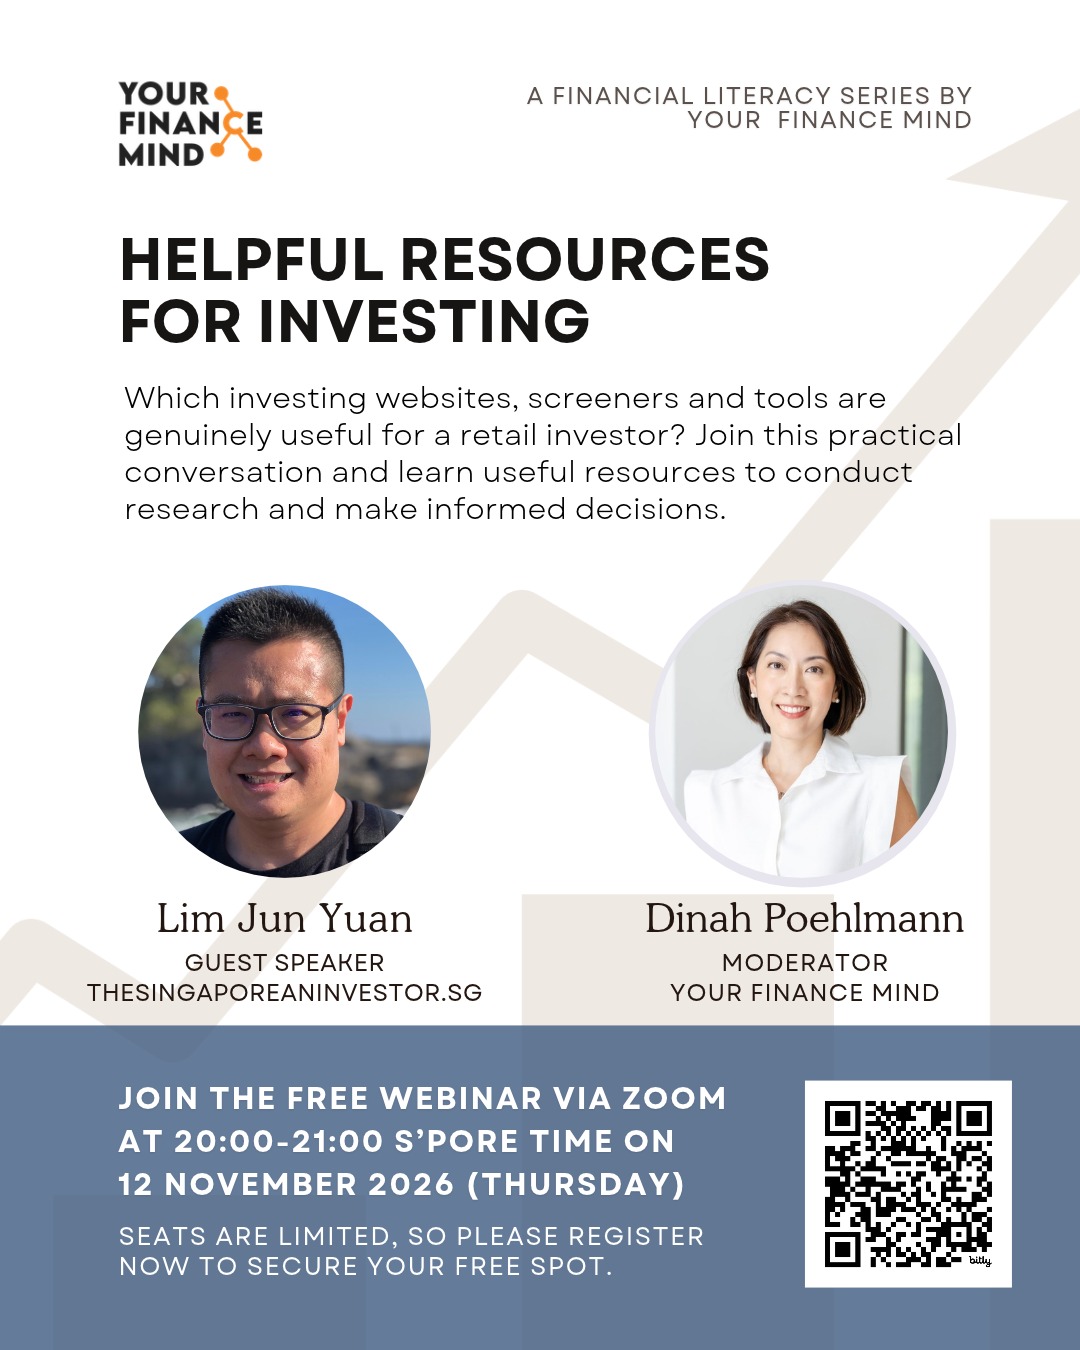
It's been quite some time since I last had a live chit-chat with the investing community, and I’m excited to be back for another session! A big thank you to my friend, Dinah Poehlmann from Your Finance Mind, for inviting me once again!
This time, we’re taking a little break from REITs and exploring some interesting topics surrounding investing, including my go-to investing resources, when is a stock considered 'investable', my thoughts about using AI for stock analysis and trading, and much more.
Whether you're just starting your investing journey or have been investing for years, I hope this session will offer some useful perspectives and practical takeaways that you can apply to your own investing journey.
Best of all, the session is completely FREE to attend! All you need to do is register in advance to receive the Zoom link:
👉 Click here to reserve your spot!
Are You Worried about Not Having Enough Money for Retirement?
You're not alone. According to the OCBC Financial Wellness Index, only 62% of people in their 20s and 56% of people in their 30s are confident that they will have enough money to retire.
But there is still time to take action. One way to ensure that you have a comfortable retirement is to invest in real estate investment trusts (REITs).
In 'Building Your REIT-irement Portfolio' which I've authored, you will learn everything you need to know to build a successful REIT investment portfolio, including a list of 9 things to look at to determine whether a REIT is worthy of your investment, 1 simple method to help you maximise your returns from your REIT investment, 4 signs of 'red flags' to look out for and what you can do as a shareholder, and more!

You can find out more about the book, and grab your copy (ebook or physical book) here...

Comments (0)