Brief Introduction:
Frasers Centrepoint Trust (SGX: J69U), or FCT, is Singapore’s largest owner of suburban retail malls.
With the exception of Central Plaza, an office property integrated with Tiong Bahru Plaza as part of a mixed-use development, the other 8 properties in FCT’s portfolio are retail malls. These malls are strategically located close to residential areas and within easy reach of public transportation amenities.
All of FCT’s properties are located in Singapore, with its portfolio collectively valued at S$8.4 billion.
Financial Figures (FY2024/25 vs. FY2025/26):
| FY2024/25 | FY2025/26 | % Variance | |
| Gross Revenue (S$’mil) | $389.6m | $444.9m | +14.2% |
| Property Operating Expenses (S$’mil) | $111.6m | $123.2m | +10.4% |
| Net Property Income (S$’mil) | $278.0m | $321.7m | +15.7% |
| Distributable Income to Unitholders (S$’mil) | $233.2m | $252.2m | +8.1% |
For the full year, FCT delivered a strong set of results, with gross revenue and net property income registering double-digit growth, while distributable income to unitholders recorded a high single-digit increase.
Gross revenue rose 14.2% year on year to S$444.9 million, while net property income grew 15.7% to S$321.7 million. The improvement was largely driven by the full-year contribution from the acquisition of Northpoint City South Wing, which was completed in May 2025.
Excluding the newly acquired property and Hougang Mall, which underwent an asset enhancement initiative a year earlier, gross revenue and net property income would have grown by 1.3% and 2.3%, respectively, supported mainly by higher passing rents across most of FCT’s malls.
Property operating expenses increased by 10.4% year on year to S$123.2 million, primarily reflecting the full-year impact of Northpoint City South Wing’s acquisition.
Distributable income to unitholders rose 8.2% year on year to S$252.2 million, after accounting for S$7.6 million retained during FY2025/26 for asset enhancement initiatives and/or general corporate and working capital requirements.
Financial Figures (2H FY2024/25 vs. 2H FY2025/26):
| 2H FY2024/25 | 2H FY2025/26 | % Variance | |
| Gross Revenue (S$’mil) | $205.2m | $223.0m | +8.7% |
| Property Operating Expenses (S$’mil) | $60.9m | $62.1m | +2.0% |
| Net Property Income (S$’mil) | $144.3m | $160.9m | +11.5% |
| Distributable Income to Unitholders (S$’mil) | $123.1m | $127.2m | +3.3% |
Looking at FCT’s financial performance in the second half of the year, the REIT continued to deliver steady growth, with gross revenue increasing by 8.7% year on year to S$223.0 million and net property income rising by 11.5% to S$160.9 million. The improvement was primarily driven by the 6-month contribution from Northpoint City South Wing, acquired in May 2025, alongside higher passing rents across most of its malls.
Excluding contributions from Northpoint City South Wing and Hougang Mall, which underwent asset enhancement works during the corresponding period a year earlier, FCT’s gross revenue and net property income would have grown by just 0.8% and 2.5% year on year, respectively.
Property operating expenses rose by 2.0% year on year to S$62.1 million, mainly reflecting the 6-month contribution from Northpoint City South Wing following its acquisition.
Meanwhile, distributions to unitholders increased by 3.3% year on year to S$127.2 million. This figure was after excluding the S$3.0 million retained in 2H FY2026/27 for asset enhancement initiatives and/or general corporate and working capital purposes.
Portfolio Occupancy Profile (3Q FY2025/26 vs. 4Q FY2025/26):
| 3Q FY2025/26 | 4Q FY2025/26 | |
| Portfolio Occupancy (%) | 99.6% | 99.7% |
| Portfolio WALE (by NLA – years) | 1.7 years | 1.8 years |
| Portfolio WALE (by Gross Rent – years) | 1.7 years | 1.7 years |
FCT maintained a very high portfolio occupancy rate of 99.7%, with all its retail properties recording occupancy rates of at least 99.0%, except for Century Square at 98.6%. Its sole office property, Central Plaza, recorded an occupancy rate of 95.4%.
Looking at its lease expiry profile over the next 3 financial years, from FY2026/27 to FY2028/29, lease renewals were well staggered, with an average of approximately 29.6% of leases due for renewal each year. Another 11.2% of leases will expire only in FY2029/30 or later, providing further visibility on the portfolio’s lease commitments.
Finally, FCT achieved a positive rental reversion of 6.6% on new and renewed leases. This should support rental income growth and contribute to the REIT’s revenue growth in the coming quarters.
Debt Profile (3Q FY2025/26 vs. 4Q FY2025/26):
| 3Q FY2025/26 | 4Q FY2025/26 | |
| Aggregate Leverage (%) | 40.4% | 36.8% |
| Interest Coverage Ratio (times) | 3.7x | 4.4x |
| Average Cost of Debt (%) | 3.2% | 3.2% |
| Average Term to Debt Maturity (years) | 3.7 years | 3.4 years |
| % of Borrowings Hedged at Fixed Rates (%) | 65.7% | 68.6% |
Following the divestment of White Sands at an 8.4% premium to its appraised value, with the proceeds used to repay borrowings, FCT’s aggregate leverage improved to a healthy 36.8%, comfortably below the regulatory limit of 50.0%.
Its interest coverage ratio also strengthened to 4.4x, up from 3.7x in the previous quarter, while the average cost of debt remained stable at 3.2%.
Meanwhile, the proportion of borrowings hedged at fixed interest rates increased by 2.9 percentage points to 68.6%. However, in my personal opinion, this remains slightly below my preferred threshold of at least 70% for REITs. With the US Federal Reserve having raised its benchmark interest rate by 0.25 percentage points in September 2026 and further hikes expected in the coming months to curb inflation, partly driven by rising oil prices, FCT could face higher borrowing costs. This may put pressure on its distributable income and potentially constrain future distribution growth for unitholders.
Distribution Payout to Unitholders (2H FY2024/25 vs. 2H FY2025/26):
| 2H FY2024/25 | 2H FY2025/26 | % Variance | |
| Distribution Per Unit (S$’cents) | 6.059 cents | 6.214 cents | +2.6% |
If you are a unitholder of FCT, do take note of the following dates on its upcoming distribution payout:
Ex-Date: 29 October 2026
Record Date: 30 October 2026
Payout Date: 27 November 2026
Distribution Payout to Unitholders (FY2024/25 vs. FY2025/26):
| FY2024/25 | FY2025/26 | % Variance | |
| Distribution Per Unit (S$’cents) | 12.113 cents | 12.350 cents | +2.0% |
Including the distribution of 6.136 cents per unit in 1H FY2025/26, FCT’s total distribution for FY2025/26 came in at 12.350 cents per unit.
Compared with the 12.113 cents per unit distributed in the previous financial year, this represented a modest 2.0% year-on-year increase.
CEO Mr Richard Ng’s Comments & Outlook (from the REIT’s Press Release):
“FCT has delivered a strong set of results for FY26, underpinned by healthy operating performance. This brings the full-year DPU to 12.35 cents, marking the highest payout since FCT’s listing in July 2006. We also made good progress in strengthening the portfolio and positioning FCT for its next phase of growth.
During the year, as part of our proactive capital recycling strategy, we divested White Sands at a premium which created debt headroom for us to re-invest part of the proceeds into the joint development of Bayshore Drive GLS site where we will develop the only retail mall within the fast-growing residential precinct with strong transport connectivity. We are excited about this opportunity for FCT to harness development as a new growth driver at an attractive yield, while at the same time securing a future acquisition opportunity for FCT.
We are also continuing to invest in our existing portfolio. Following the successful completion of the Hougang Mall AEI in September 2026, we are on track to complete the Phase 1 AEI at NEX by end of 2026, and planning for the Causeway Point AEI, which is expected to commence in the second quarter of 2027. These initiatives strengthen the appeal of our malls as social hubs, enhancing their long-term relevance and competitiveness. Together with our healthy financial position, they underpin our ability to deliver resilient performance and sustainable long-term value to our Unitholders.”
Closing Thoughts:
FCT delivered a resilient set of financial results for both the second half and the full financial year, supported by the contribution from its newly acquired Northpoint City South Wing, alongside improved contributions from its existing properties.
Occupancy across its portfolio remained exceptionally high, with all its retail malls recording occupancy rates of at least 99.0%. The REIT also continued to achieve positive rental reversions on new and renewed leases, which should support steady growth in its financial performance over the coming quarters.
FCT’s debt profile also remained healthy, with aggregate leverage of 36.8%, comfortably below the regulatory limit of 50.0%. This provides the REIT with financial headroom to pursue portfolio expansion opportunities when they arise. One area for improvement, however, is the proportion of borrowings hedged at fixed interest rates. With 31.4% of its borrowings still exposed to floating interest rates, FCT could face higher borrowing costs if the US Federal Reserve raises benchmark interest rates further, potentially limiting the growth of distributions to unitholders.
As a unitholder, I appreciate FCT’s measured approach to carrying out asset enhancement initiatives across its malls, focusing on one property at a time in recent years. Following Tampines 1, which was completed in August 2024, and Hougang Mall, completed in September 2026, the REIT is now progressing with enhancements at nex, with Phase 1 expected to be completed by end-2026 and Phase 2 scheduled to commence in January 2027 and finish in 1Q 2028. This will be followed by Causeway Point, where works are scheduled to begin in 2Q 2027 and conclude in 2Q 2029.
I believe this phased approach allows FCT to progressively enhance its malls while managing the impact of renovation works on its portfolio. Upon completion, these initiatives should strengthen the malls’ contributions and support the REIT’s financial performance over the coming years.
Related Documents:
Press Release
Financial Statements
Presentation Slides
Disclaimer: At the time of writing, I am a unitholder of Frasers Centrepoint Trust.
Join Me for a FREE Live Online Chit-Chat on Thursday, 12 November, from 8–9pm (SGT)!
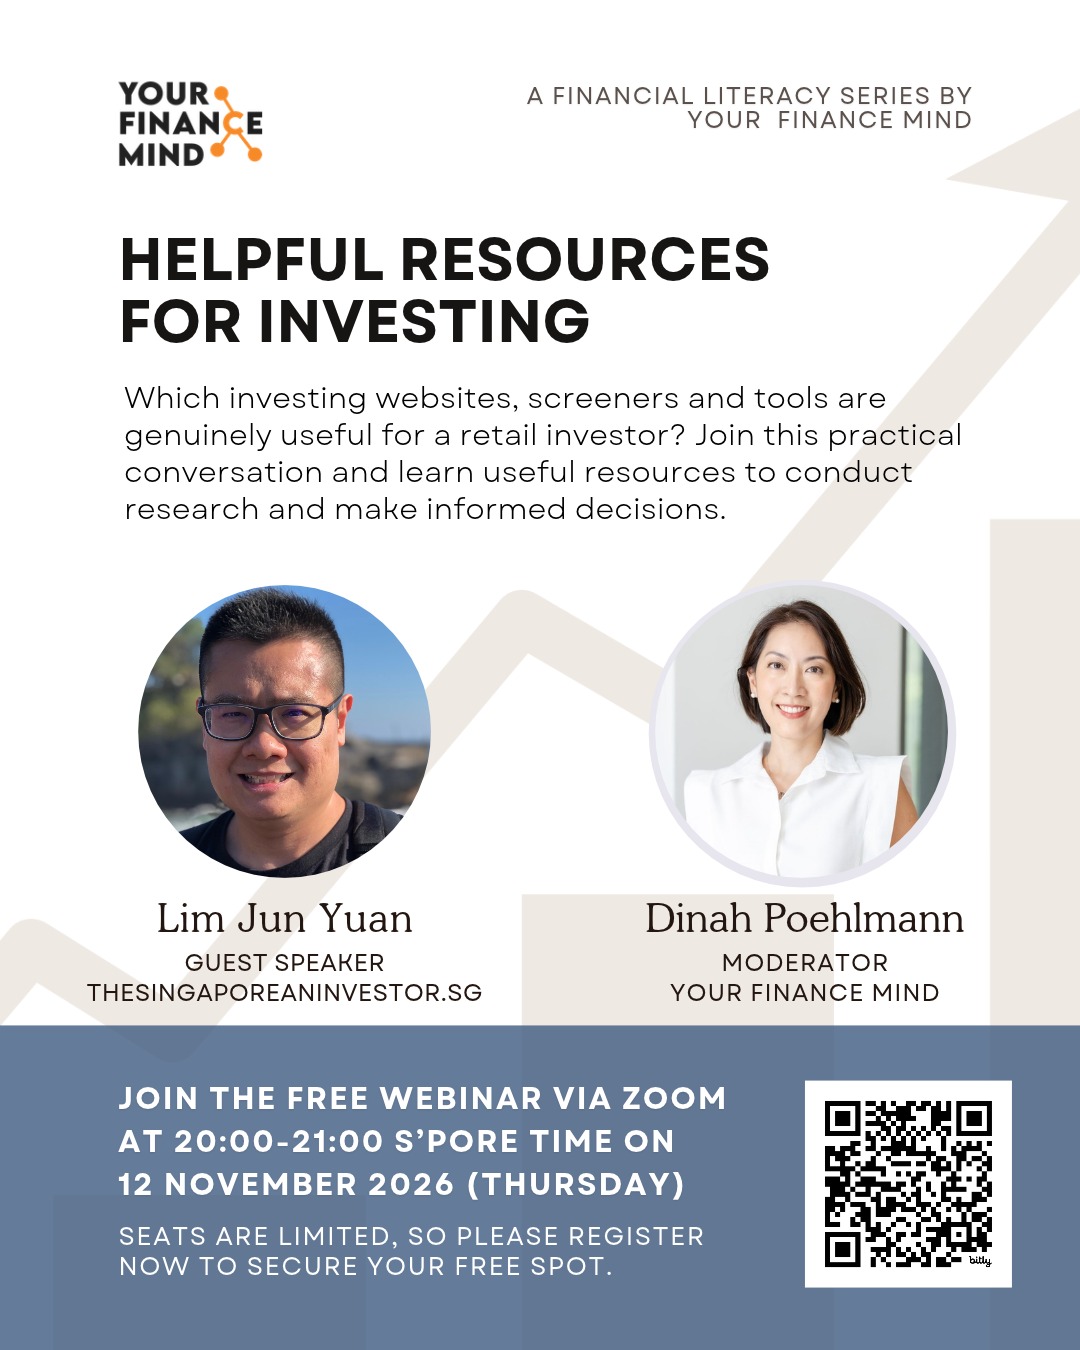
It's been quite some time since I last had a live chit-chat with the investing community, and I’m excited to be back for another session! A big thank you to my friend, Dinah Poehlmann from Your Finance Mind, for inviting me once again!
This time, we’re taking a little break from REITs and exploring some interesting topics surrounding investing, including my go-to investing resources, when is a stock considered 'investable', my thoughts about using AI for stock analysis and trading, and much more.
Whether you're just starting your investing journey or have been investing for years, I hope this session will offer some useful perspectives and practical takeaways that you can apply to your own investing journey.
Best of all, the session is completely FREE to attend! All you need to do is register in advance to receive the Zoom link:
👉 Click here to reserve your spot!
Are You Worried about Not Having Enough Money for Retirement?
You're not alone. According to the OCBC Financial Wellness Index, only 62% of people in their 20s and 56% of people in their 30s are confident that they will have enough money to retire.
But there is still time to take action. One way to ensure that you have a comfortable retirement is to invest in real estate investment trusts (REITs).
In 'Building Your REIT-irement Portfolio' which I've authored, you will learn everything you need to know to build a successful REIT investment portfolio, including a list of 9 things to look at to determine whether a REIT is worthy of your investment, 1 simple method to help you maximise your returns from your REIT investment, 4 signs of 'red flags' to look out for and what you can do as a shareholder, and more!

You can find out more about the book, and grab your copy (ebook or physical book) here...

Comments (0)